Set firm limits on your discretionary spending
Establishing control over daily spending is rarely a matter of willpower or rigid self-denial. Most budgets fail because individuals rely on vague mental resolutions while navigating environments engineered for frictionless checkout.
Contactless cards, one-click online purchases, and algorithmic retail marketing constantly bypass conscious deliberation. Regaining sovereignty over your remaining take-home pay requires physical barriers, practical transaction friction, and unambiguous spending rules that protect your essential funds from spontaneous impulse decisions.
The mechanics of frictionless overspending
Sub-second transaction speed
Modern payment rails have systematically stripped away the physical resistance that once governed retail commerce. Tapping a plastic card or scanning a smartphone against an electronic terminal takes less than two seconds, obscuring the transfer of hard-earned wages.
The digital loss disconnect
When you spend digital money, your brain does not register the immediate loss in the same way it does when parting with physical cash. The transaction feels like a harmless confirmation tone rather than a tangible reduction in your monthly security reserve.
Engineering intentional hesitation
Recognising that modern checkout technologies are specifically designed to reduce financial hesitation is the first step toward building deliberate friction into your purchasing habits. You must construct your own artificial boundaries where payment networks removed them.
Implementing strict weekly spending allowances
Distributing an entire month's discretionary spending money in a single opening balance invites miscalculation. Break your monthly surplus into seven-day operational allocations.
Defined operational category caps
The allowance must cover all casual food, socialising, fuel, and minor retail consumables. Transfer only one week's allowance onto your everyday debit card every Monday morning, leaving fixed commitments segregated in a protected bill account.
The Thursday exhaustion stop
If your balance drops to zero by Thursday evening, your discretionary spending ceases until the following Monday. No topping up from savings or pulling forward from next week. You cook from the pantry and refuse paid outings until the new cycle starts.
Zero rollover policy
Unspent allowances do not roll over to create spending binges; they divert straight into emergency savings. Treating leftover money as a baseline sweep reinforces structural discipline and gradually builds your liquidity reserve.
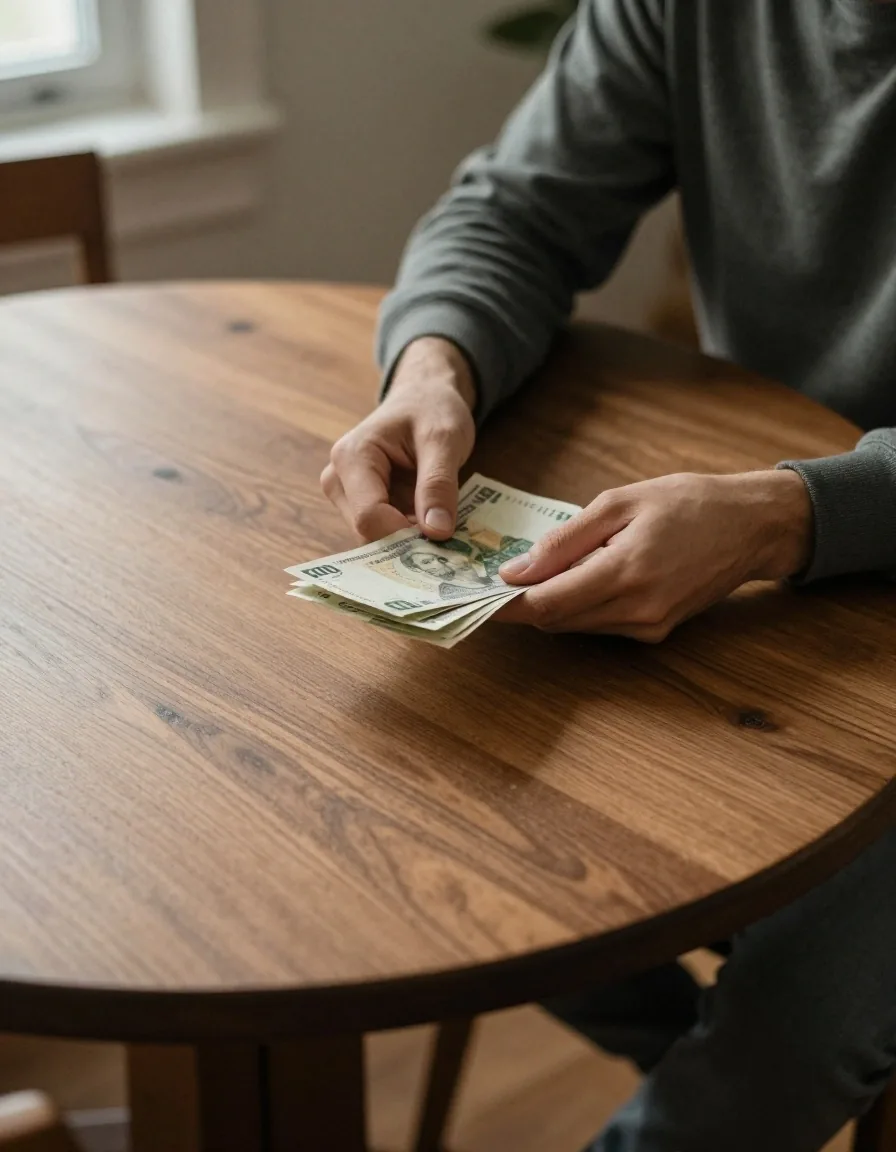
Holding paper notes restores the physical weight of transaction loss during casual outings.
Re-introducing tangible cash for vulnerable categories
Certain spending categories are exceptionally vulnerable to runaway card tapping, particularly social drinking, casual dining, and incidental supermarket visits. For these specific trouble zones, consider temporarily withdrawing your allocated weekly allowance in paper bank notes.
Carrying physical money creates tactile, visible feedback every time you open your wallet. Watching the physical pile of banknotes diminish across the week provides an unmistakable visual indicator of your remaining resources, instantly re-establishing conscious spending discipline.
When a twenty-pound note leaves your hand, there is an inescapable physical subtraction. The friction of receiving change and monitoring empty wallet slots prevents casual overspending before it begins.
Introducing mandatory cooling-off intervals
Spontaneous retail purchases are driven by temporary emotional impulses that typically dissipate when forced to wait. Establish an uncompromising seventy-two-hour rule for any non-essential purchase exceeding thirty pounds.
Record & walk away
When you feel an impulse, write down the product name, retailer, and exact cost in a physical notebook, then immediately exit the store or app.
Thermal dissipation
Allow three full calendar days to elapse. The dopamine-driven surge will fade, exposing whether the item holds real utility.
Deliberate execution
If the purchase still appears rational, necessary, and affordable from your active week's allowance, you may proceed without guilt.
Removing stored payment credentials
Online digital retailers maintain profitability by making repeat transactions as effortless as possible. Stored card details, automated autofill forms, and one-click purchasing options allow you to finalise orders before rational objections surface.
Audit your web browsers, shopping apps, and payment intermediaries, systematically deleting all saved card credentials and disabling biometrics for shopping checkouts. Forcing yourself to manually locate a card, input sixteen digits, and enter validation codes introduces vital thinking time that stops impulsive late-night transactions.
Establishing hard boundaries against workplace convenience traps
Working environments are filled with routine spending traps that quietly drain weekly cash allowances. Buying morning coffees, picking up packaged meal deals, purchasing mid-afternoon snacks, and contributing to constant workplace collections can easily consume thirty to forty pounds each week.
Prepare lunch items at home during evening dinner prep, carry a refillable thermal beverage cup, and budget an explicit monthly envelope for office social events. Containing these minor professional expenses preserves your capital for meaningful personal priorities.
Managing social pressures and boundary setting
Financial strain often stems from the fear of social embarrassment when declining expensive group activities with peers, colleagues, or family members. Attempting to match the dining, travel, or entertainment habits of individuals with higher earnings or higher debt tolerances rapidly ruins household budgets.
Practice concise, boundary-focused communication: offer affordable alternatives, such as hosting dinner at home or meeting for a walk, rather than silently agreeing to expensive venue bookings. Protecting your financial health requires asserting comfortable boundaries around social expenditures.
"That venue is outside what I've allocated for this week. Why don't you come over for coffee or join me for a walk along the canal?"
Reviewing weekly expenditure without self-recrimination
Setting spending boundaries is a practical skill that improves through practice rather than an all-or-nothing moral test. If you slip up and exceed your weekly allowance on a spontaneous social outing, avoid abandoning the entire household plan in frustration.
Acknowledge the spending leak, examine the specific trigger that bypassed your boundaries, and deduct the deficit directly from the following week's allowance. Consistent, dispassionate accountability keeps temporary lapses from turning into permanent budgetary failures.
Overspend in Week 1 = Direct deduction from Week 2 allocation. Essential bill balances remain untouched.
Discretionary Spending Principles FAQ
What happens if an unavoidable emergency arises during the week? +
Can I keep my discretionary allowance in my main salary account? +
How do I determine the appropriate weekly figure? +
What if my income fluctuates unpredictably each month? +
Establish your allocation boundaries today
Protect your essential living commitments by applying deliberate friction to every casual payment channel. Explore our comprehensive budgeting frameworks to coordinate your complete household ledger.